The Division’s Fiscal Year 2027 Examination Priorities retain the fundamental focus areas from prior years – including investment advisers’ fiduciary obligations and compliance program effectiveness, Regulation Best Interest, broker-dealer financial responsibility rules and cybersecurity – but the frontier has shifted. “Super intelligence,” complex and illiquid products, Treasury clearing, and payments to finders and personal services
PCAOB Proposes Changes to Negative Assurance in Comfort Letters Responding to Semiannual Reporting Proposal
On November 3, 2026, the Public Company Accounting Oversight Board (“PCAOB”) voted unanimously to propose targeted amendments to AS 6101, Letters for Underwriters and Certain Other Requesting Parties, the standard governing auditor comfort letters. Notably, the proposal would change the rule that permits auditors to provide negative assurance on subsequent changes in financial statement items
SEC Remarks at the Small Business Capital Formation Advisory Committee Meeting: The IPO Modernization Initiative and Regulation Crowdfunding
At the October 27, 2026 meeting of the Securities and Exchange Commission’s (the “SEC”) Small Business Capital Formation Advisory Committee (the “SBCFA”), Chair Paul S. Atkins and Commissioner Mark T. Uyeda discussed the SEC’s initial public offering (“IPO”) modernization initiative, specifically, easing the gun-jumping prohibitions, as well as re-evaluating Regulation Crowdfunding (“Reg CF”).
Turning to
Amendments to FINRA Rule 2210 Permit Use of Projected Performance and Targeted Returns in Broker-Dealer Communications Subject to Specified Conditions
On October 15, 2026, the Securities and Exchange Commission (“SEC”) approved amendments to Rule 2210 (Communications with the Public) of the Financial Industry Regulatory Authority, Inc. (“FINRA”), allowing member firms to project performance or provide a targeted return with respect to a security, a securities portfolio, or an asset allocation or other investment strategy in
SEC Staff Highlights Fair Value and Disclosure Considerations for Private Assets
The staff of the Securities and Exchange Commission, including the Office of the Chief Accountant and the Division of Investment Management (the “Staff”), recently issued a Statement on Fair Value Measurement and Disclosure Considerations for Private Assets (the “Statement”). The Statement highlights considerations for applying Financial Accounting Standards Board (“FASB”) Accounting Standards Codification (“ASC”) Topic
No Exit: Other Reasons to Stay Private
In No Exit, a recent paper, authors Brian J. Broughman, Matthew T. Wansley, and Samuel N. Weistein, describe how increased antitrust restrictions caused a decline in M&A exits by startups. However, instead of this leading to an increase in IPOs, companies remained private and used alternatives to access capital and liquidity.
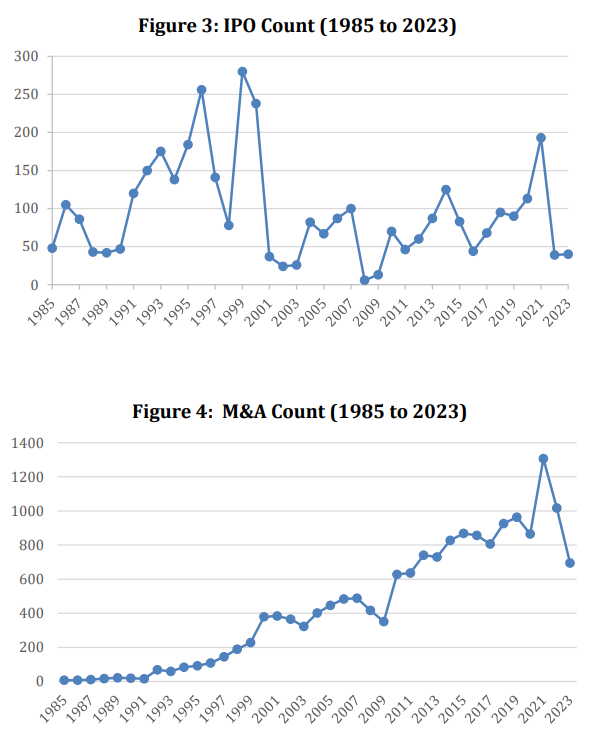
Source: Broughman, Wansley
SIFMA Webinar: SEC Re-Proposal on Conflicts of Interest in Securitization
June 20, 2023 Webinar
1:00 pm – 2:00 pm ET
Register here.
Earlier this year, the SEC re-proposed a rule to implement Section 27B of the Securities Act of 1933, a provision added by Section 621 of the Dodd-Frank Act.
This Dodd-Frank provision, intended to prohibit certain conflicts of interest in securitization transactions, is
Upcoming SEC Open Meeting May 3, 2023
The Securities and Exchange Commission will hold an open meeting on May 3, 2023 at 10 a.m., which will be available to via webcast, the link will be posted shortly before the start of the meeting on the SEC website.
The Division of Corporation Finance will present on share repurchase disclosure modernization. The Commission will
Upcoming SEC Open Meeting
The Securities and Exchange Commission will host an open meeting on March 22, 2023 at 10 a.m, which will be open to the public via webcast on the SEC website. The Division of Investment Management will present on Enhancing Private Fund Reporting. The Commission will consider whether to adopt amendments to Form PF, the
SEC Accounting Standard Setting Statement
The SEC’s Chief Accountant Paul Munter, released a statement “Accounting Standard Setting in a Rapidly Evolving Business Environment: A Focus on the Timely Delivery of Investor Priorities,” discussing improvements to Financial Accounting Foundation (“FAF”) and the Financial Accounting Standards Board (“FASB”) accounting standards and standard-setting processes since the SEC’s statement last year.
Since