On November 3, 2026, the Public Company Accounting Oversight Board (“PCAOB”) voted unanimously to propose targeted amendments to AS 6101, Letters for Underwriters and Certain Other Requesting Parties, the standard governing auditor comfort letters.  Notably, the proposal would change the rule that permits auditors to provide negative assurance on subsequent changes in financial statement items only as of a date less than 135 days after the end of the most recent period for which the auditor performed an audit or review.  The proposal responds directly to the SEC’s May 2026 semiannual reporting proposal, which can be found here and was discussed in our prior blog post, and follows the PCAOB’s June 23, 2026 Request for Public Comment.

Under existing AS 6101, if an issuer seeks to raise capital 135 days or more after the end of the most recent audited or reviewed period, but before its next periodic financial statements are filed, the auditor cannot provide negative assurance in a comfort letter on subsequent changes.  This gap would be further exacerbated by the SEC’s proposal to allow companies to elect semiannual instead of quarterly reporting.  The period between the end of the semiannual period and the annual report filing deadline could be up to 274 days.  The SEC also proposed a small non-accelerated filer subcategory that would have 120 days following fiscal year-end to file its annual reports; for these companies, the period between the end of the third quarter and the annual report deadline would be 212 days.
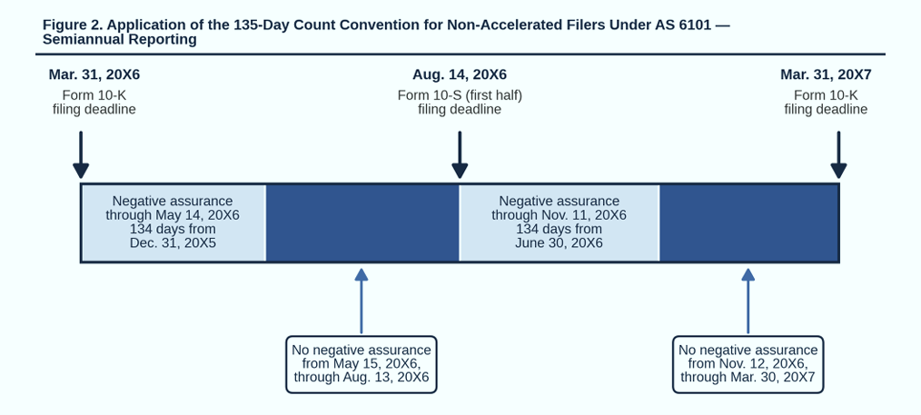
The proposed targeted amendments to AS 6101 would create a filing-based window, continue to exclude late filers, and add a new note on auditor judgment.

Amended AS 6101.46 would permit negative assurance in a comfort letter as of any date after the end of the most recent audited or reviewed period and before the date by which financial statements for the next annual or interim period are required to be filed.  This would eliminate the current gaps in which auditors cannot provide negative assurance and would better align with proposed semiannual reporting.
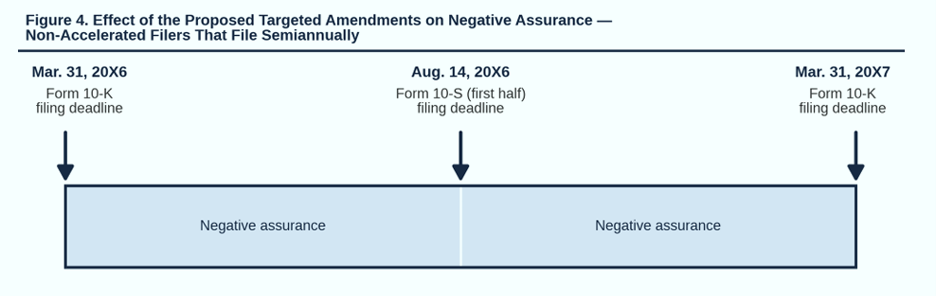
However, under amended AS 6101.47, late filers would remain excluded.  If the next required financial statements were due but not filed, the auditor could not provide negative assurance and would be limited to reporting the procedures performed and findings obtained.  Finally, a new note to AS 6101.46 would confirm that negative assurance is permitted but not required, and would list factors that may inform the auditor’s decision.  These factors include the length of time since the last audit or review, management’s ability to respond to inquiries through the specified date, changes in senior management or key personnel, the effectiveness of internal control over financial reporting, going concern considerations, restatement activity, and the appointment of a new auditor. The proposal would not change what constitutes negative assurance or expand required auditor procedures.

Despite the link to the SEC’s semiannual reporting proposal, the PCAOB states that it is not necessary to wait for final SEC action, because the amendments would also close existing gaps for quarterly filers.

The PCAOB is seeking comment on all aspects of the proposal, including whether it should be adopted even if the SEC does not adopt semiannual reporting, its economic consequences, its application to emerging growth companies, and the appropriate effective date. Comments are due by January 4, 2027, and any final amendments will require SEC approval before taking effect.

Read PCAOB Release No. 2026-008 here. 

On November 3, 2026, the staff (the “Staff”) of the Division of Corporation Finance (the “Division”) of the Securities and Exchange Commission (the “SEC”) issued a no-action letter (the “No-Action Letter”) regarding Canton Coin.  Digital Asset Holdings, LLC (“DA”) created the Canton blockchain protocol and developed the technology for Canton Coin, the native digital asset of the Canton Network.  In the No-Action Letter, the Staff determined that Canton Coin is a “digital commodity,” as described in the SEC’s March 2026 interpretive release (the “Interpretation”), and, therefore, is not a “security” under Section 2(a)(1) of the Securities Act of 1933, as amended (the “Securities Act”), or Section 3(a)(10) of the Securities Exchange Act of 1934, as amended (the “Exchange Act”).  For these purposes, a “digital commodity” is “a crypto asset that is intrinsically linked to and derives its value from the programmatic operation of a crypto system that is functional, as well as supply and demand dynamics, rather than from the expectation of profits from the essential managerial efforts of others […] that does not have intrinsic economic properties or rights.”

In reaching this determination, the Staff highlighted (i) the absence of a “central party,” a concept addressed in its recent frequently asked questions (the “FAQs”) (discussed here and here), and (ii) the fact that Canton Coin is intrinsically linked to, and derives its value from, the programmatic operation of the Canton Network, as well as supply and demand dynamics, rather than from the expectation of profits from the essential managerial efforts of others.  The Staff also stated that it will not recommend enforcement action if Canton Coin is minted programmatically by Super Validators, Validators, and application providers, in the manner and under the circumstances described in the incoming letter, without registration under Section 5 of the Securities Act or Section 12(g) of the Exchange Act.

Key Facts in the Incoming Letter

The incoming letter walks through each element of the digital commodity description in the Interpretation and offers a useful roadmap of the “investment contract” analysis under the Howey test.  Specifically, “Canton Coin is intrinsically linked to and derives its value from the programmatic operation of a crypto system, the Canton Network, which is functional and was functional upon launch.”

Canton Coin is a “Digital Commodity”

  • Functionality at launch.  Canton Coin was launched only after the Canton Network was functional. There was no initial coin offering, pre-mine, or other pre-launch sale or allocation.  Since the network launched in June 2024, all Canton Coin has been minted programmatically by network participants based on network activity.
  • Intrinsic link to the programmatic operation of the Canton Network.  Canton Coin is used to pay network fees for the Global Synchronizer, and it incentivizes Super Validators, Validators, and application providers to supply infrastructure and application activity; the token’s price is designed to track network usage.  No portion of the Canton Coin used to pay fees is received by DA, the Canton Foundation (described further below), or anyone else.
  • The value derives from the programmatic operation of the Canton Network and from supply and demand dynamics.  New Canton Coin enters circulation only through protocol-defined minting, while all Canton Coin used to pay network fees is burned.  Demand comes mainly from participants that need Canton Coin to pay those fees.  As a result, Canton Coin’s price is expected to align with the network’s utility over the long run.
  • No central party.  Any change to the protocol, including minting parameters and the admission of new Super Validators, requires the approval of at least two-thirds of the Super Validator Node Operators. As of September 30, 2026, there were 13 Super Validator Node Operators and approximately 60 Super Validators.  Each Super Validator Node Operator has one vote, regardless of how many Super Validators it hosts or how much Canton Coin it holds. DA operates two of the 13 Super Validator Nodes, but represented that it cannot unilaterally dictate consensus outcomes. The Canton Foundation, a non-profit entity, facilitates governance and hosts committees, including a tokenomics committee that determines the economic parameters for Canton Coin. No “central party” exists with respect to the Canton Network because no person, including the Canton Foundation and DA, has operational, economic, or voting control of the Canton Network.
  • No intrinsic economic characteristics of a security.  Canton Coin conveys no right to future income, profits, or assets of DA, the Canton Foundation, any Super Validator, any application provider, or any other enterprise, promisor, or obligor, nor does holding Canton Coin passively accrue yield.

Programmatic Minting of Canton Coin by Super Validators, Validators and Application Providers Are Not Transactions Involving “Investment Contracts” Under Howey

The incoming letter focuses on the third prong of Howey, whether there is a reasonable expectation of profits derived from the entrepreneurial or managerial efforts of others, and notes that the failure of any one element defeats the existence of an investment contract.

  • Rewards reflect participants’ own efforts.  Any profit expectation of Super Validators, Validators, and application providers is based on their own efforts, because rewards are tied to each participant’s own measured activity.  An application that drives no activity earns nothing.  The incoming letter also characterizes the services of Super Validators and Validators as administrative or ministerial, consistent with the Interpretation’s treatment of protocol mining, and notes that no sponsor or promoter calculates, pays, or plays a necessary role in disbursing rewards.
  • No essential managerial efforts after functionality.  The incoming letter relies on Question 2.3 of the FAQs, in which the Division stated that, once a crypto system is functional, services to secure, maintain, improve, or enhance the system, or to facilitate network effects, would not involve essential managerial efforts.  Because the Canton Network was functional at launch and there was no pre-launch sale, the incoming letter concludes that there was no pre-functional period in which purchasers could have formed profit expectations tied to promised managerial efforts, and that the ongoing support from DA, the Canton Foundation, and others does not constitute essential managerial efforts.

Takeaways

While the No-Action Letter is one example of how the Staff may apply the digital commodity framework in the Interpretation to a specific token, it remains to be seen whether the Staff will provide similar analysis with regard to other tokens.  What is clear, however, is that the Staff is interested in providing guidance and clarity to those in the crypto space, and that this area remains one to watch.

Access the No-Action Letter: Canton Coin No-Action Letter.

Access the Incoming Letter: Canton Coin Incoming Letter.

Webinar | November 12, 2026
11:45 p.m. – 1:00 p.m. EST
Register here.

Each proxy season brings new disclosure priorities and investor expectations, and 2027 will be no exception. The SEC is rethinking the shareholder proposal process, proposing optional semiannual reporting and broader scaled disclosure, and starting a wider review of Regulation S-K. Boards and compliance teams are also facing new risks, particularly in the areas of AI and cybersecurity, which raise questions about disclosure, board oversight and the scope of internal policies.

Join experts from Mayer Brown and Georgeson for a free CLE-eligible webinar, hosted by Intelligize, on Thursday, November 12, 2026 at 11:45 a.m. EST.

In this session, the panel will cover the developments shaping the 2027 season and give practical guidance for Form 10-K and proxy statement drafting, governance and compliance policy updates and investor engagement.

In this session, attendees will:

  • Gain a fundamental understanding of recent proxy statement and annual report developments, and what is likely to apply in 2027
  • Learn how to handle shareholder proposals now that the SEC staff no longer responds to Rule 14a-8 no-action requests and has proposed rescinding Rule 14a-8
  • Learn about risk factor disclosure trends, including cybersecurity, artificial intelligence, and other emerging topics
  • Gain insight into shareholder proposal trends, proxy advisor developments and voting outcomes from the 2026 season, and what to expect in 2027, including related litigation risks

On October 29, 2026, the Staff of the Division of Investment Management (the “Staff”) of the Securities and Exchange Commission (the “SEC”) issued a no-action letter to Goldman Sachs Asset Management, L.P. (“GSAM”) addressing warehouse arrangements entered into in connection with the launch of registered closed-end funds and business development companies (“BDCs”).  The letter confirms that the Staff will not recommend enforcement action to the SEC under Sections 17(d) and 57(a)(4) of, and Rule 17d-1 under the Investment Company Act of 1940, as amended (the “1940 Act”), if GSAM enters into the warehouse arrangement described in the letter.

Under the proposed arrangement, GSAM would identify investment opportunities for G-X Private Markets (the “Fund”) and present these to an unaffiliated (i.e., neither an affiliated person of the Fund (as defined in Section 2(a)(3) of the 1940 Act (a “first-tier affiliate”), nor an affiliated person of an affiliated person of the Fund (a “second-tier affiliate”)) warehouse party that would have discretion to acquire the investments.  The investments would consist of assets that are consistent with the Fund’s investment objective and strategies. In effecting the warehousing arrangement and any acquisition of investments, GSAM would comply with its policies and procedures relating to investment allocation, as applicable.

The warehouse party would hold the investments until the Fund satisfies a minimum offering requirement and the Fund’s board of trustees approves the Fund’s acquisition of the investments.  The Fund would then acquire all of the investments held by the warehouse party under the arrangement. The Fund would enter into only one facility agreement with one warehouse party.

The Staff’s position is subject to numerous and specific conditions designed to address the provisions of Sections 17(d) and 57(a) of the 1940 Act, which are intended to guard against the types of conflicts of interest and overreaching by affiliates, which these sections were intended to prevent.  Those conditions include that the warehouse party must be unaffiliated with the Fund and investments may not be acquired from affiliates of the Fund (i.e., the investments may not be acquired by the warehouse party from a first- or second-tier affiliate of the Fund) or from accounts managed by GSAM affiliates. This condition likely addresses, indirectly, certain arrangements that some funds have entered into, in an effort to season certain portfolio investments, raise initial capital or for other reasons.

The Fund’s board must also approve the facility agreement (and any related costs and expenses to be borne by the Fund, after receiving a copy of the facility agreement). If the Fund’s board has yet to be constituted, under state law, the Fund’s sole initial trustee has the authority to enter into agreements on the Fund’s behalf, which the fully constituted board would ratify once it has been seated.

Continue reading.

On November 2, 2026, the Staff of the Division of Corporation Finance (the “Division”) of the Securities and Exchange Commission (the “SEC”) added new Questions 1.4 through 1.6 to its frequently asked questions (the “FAQs”) on how the federal securities laws apply to certain crypto assets and certain transactions involving crypto assets (read about the original FAQs here). 

By way of background, as set forth in the SEC’s March 17, 2026 interpretive release (the “Interpretive Release”), “a digital commodity is a crypto asset that is intrinsically linked to and derives its value from the programmatic operation of a crypto system that is ‘functional,’ as well as supply and demand dynamics, rather than from the expectation of profits from the essential managerial efforts of others.”  A digital commodity is used to facilitate and incentivize the validation, ordering, and confirmation of transactions on the functional crypto system, and so is necessary for the operation of the functional crypto system.  The functional crypto system does not have a “central party” that oversees participation or distributes rewards to users, meaning that the value of a digital commodity is intrinsically linked to the programmatic functioning of the system. The new FAQs address the concept of a “central party,” which the SEC defined as a “person, entity, or group of persons or entities having operational, economic, or voting control of a crypto system.” 

The new FAQs provide the following key guidance:

Broad-Based Governance Participants as a “Group”

Whether the participants in a functional crypto system’s broad-based governance system are a “group of persons or entities” for purposes of the “central party” definition is a facts and circumstances determination. However, participants generally will not be considered a group if they are not affiliated and do not have an agreement, arrangement, or understanding (whether formal or informal) to act in concert (including through delegation) separate from their participation in the broad-based governance system itself.

The FAQs define a “broad-based governance system” as a transparent, rules-based system that permits and results in a wide and diverse group of a crypto system’s stakeholders of multiple types (e.g., developers, node operators, validators/miners, and/or holders of the crypto system’s native crypto asset) to independently contribute and form consensus or reach binding agreement regarding decisions involving the crypto system.

The same is true where the broad-based governance system is part of an organization, association, or foundation and participation is based on holding the crypto system’s native crypto asset, although the organization, association, or foundation could itself be a central party if it has operational, economic, or voting control over another crypto system. In any event, even participants that are considered a group would need to have operational, economic, or voting control of the functional crypto system to be a central party.

The Staff noted that this view pertains exclusively to the description of digital commodities in Section III of the Interpretive Release and has no relevance to provisions of the Securities Act or the Exchange Act.

Overseeing Participation

A central party oversees participation in a crypto system when it has the authority to control access to the crypto system at any level, whether at the protocol, validator, or user level.  For example, a central party oversees participation when it has unilateral authority to grant or limit access to the crypto system; determine or change the voting processes for software upgrades, protocol changes, or distributions of the native crypto asset; control who can participate in the consensus mechanism to validate transactions; or modify the crypto system’s rules-based code, reverse transactions, or revoke access.  By contrast, a central party generally does not oversee participation where every material aspect of the crypto system’s ongoing operation is executed automatically pursuant to rules-based code without discretion by any person, or where any discretion is exercised solely through a broad-based governance system whose participants are not themselves a central party.

Relationship Between “Functional” and “Decentralized”

The Interpretive Release provides that a digital commodity is necessary to participate in or use certain aspects of an associated functional crypto system, and also separately states that a digital commodity may be native to a crypto system that is decentralized. For purposes of Section III of the Interpretive Release, “functional” and “decentralized” are distinct concepts that address different aspects of a crypto system’s design and operation. A crypto system is “functional” if its native crypto asset can be used on the system in accordance with the system’s programmatic utility, and is “decentralized” if it functions and operates autonomously with no person, entity, or group of persons or entities having operational, economic, or voting control of it. Because a functional crypto system does not have a central party that oversees participation or distributes rewards to users, and a digital commodity may be native to a functional crypto system that is decentralized, a functional crypto system to which a digital commodity is native has characteristics of decentralization, although the degree of decentralization can vary depending on the facts and circumstances.

Access the FAQs: Division of Corporation Finance FAQs on Crypto Assets.

Access the Interpretive Release: Interpretive Release.

At the October 27, 2026 meeting of the Securities and Exchange Commission’s (the “SEC”) Small Business Capital Formation Advisory Committee (the “SBCFA”), Chair Paul S. Atkins and Commissioner Mark T. Uyeda discussed the SEC’s initial public offering (“IPO”) modernization initiative, specifically, easing the gun-jumping prohibitions, as well as re-evaluating Regulation Crowdfunding (“Reg CF”).

Turning to the SBCFA’s agenda, Chair Atkins began by highlighting the SBCFA’s recommendations from its July meeting on three SEC proposals:  optional semiannual reporting, simplification of filer status, and registered offering reform.  He noted these reforms aim to encourage companies to go public and stay public, and that he was now turning to another component of the IPO modernization initiative: removing unnecessary barriers during the IPO process.

In line with this, Chair Atkins discussed the gun-jumping prohibitions, describing these as “among the most restrictive regulations… contained in the Securities Act.”  Noting that the SEC has not revisited its communications rules since 2005, Chair Atkins stated that the SEC will (i) re-evaluate limits on the content of communications and on the persons to whom communications may be made, (ii) consider providing brighter lines as to when communications constitute “offers,” and (iii) consider cure provisions for issuers that violate the communications rules.  As discussed in a prior blog post, Chair Atkins raised similar concerns in his speech at Stanford, at which he solicited public comment on modernizing the IPO process.  In response to that request for comment, the Federal Regulation of Securities Committee of the Business Law Section of the American Bar Association addressed a number of aspects related to the IPO process, including the need to modernize the framework for offering related communications in Annex A of its August 4, 2026, comment letter (the “ABA Comment Letter”).  The ABA Comment Letter emphasized that, given the passage of time and technological changes, the SEC should reconsider the communications safe harbors, particularly those related to gun-jumping.

The ABA Comment Letter also noted that the SEC should reconsider the research safe harbors.  These concerns align with Commissioner Uyeda’s comments on the tension between the strict rules governing company communications with investors before and during an IPO and the lack of research coverage after the IPO.  He called for encouraging thoughtful, high-quality research coverage of smaller companies.

Chair Atkins and Commissioner Uyeda also discussed Reg CF, which the SEC adopted in 2015 to provide an avenue for startups and small businesses to raise modest amounts of capital from the “crowd.”  Chair Atkins noted that, over the past decade, there have been more than 9,800 Reg CF offerings, raising an average of $364,000 per offering.  He stated that he has directed the SEC staff to consider which components of Reg CF can be amended to reduce compliance burdens and to make Reg CF a more attractive route for issuers and investors.  Commissioner Uyeda added that, rather than focusing on raising the Reg CF offering limit, the SBCFA should consider the costly requirements associated with Reg CF and post-offering issues, such as limits on resale.

Both Chair Atkins and Commissioner Uyeda expressed interest in hearing the SBCFA’s views on these topics.  Read Chair Atkins’s speech, Commissioner Uyeda’s speech, and the ABA Comment Letter.

Hybrid | November 3, 2026
Register here.

Practising Law Institute (PLI) will host the 2026 Fintech and Regtech in the Financial Services Industry: Current Issues for Investment Advisers and Broker-Dealers program.

Mayer Brown Partner Steffen Hemmerich will participate in the “Artificial Intelligence and the Regulatory Round-Up — SEC, FINRA and Related Rulemaking” session.

See the event webpage for information on the program and the session.

Pursuant to the general instructions to Form S-3, an issuer must have been subject to the reporting requirements of Section 12 or 15(d) of the Securities Exchange Act of 1934, as amended (the “Exchange Act”), for at least the prior 12-month period to meet the eligibility requirements for the form.  However, in a welcome expansion of existing guidance, on October 26, 2026, the Staff of the Division of Corporation Finance of the U.S. Securities and Exchange Commission granted no-action relief and published a related Corporation Finance Interpretation, or CFI, providing that this requirement can be satisfied if an issuer that is “voluntarily reporting” timely filed all Exchange Act reports that it otherwise would have been required to be filed during the past 12 months, but was not subject to Section 12 or 15(d) for some of that period. 

In its letter to the Staff, Sumisho Air Lease Corporation (“Sumisho Air”) explained that its reporting obligation under Section 15(d) of the Exchange Act is expected to be automatically suspended by operation of Section 15(d) (i.e., with no action by the company) on January 1, 2027, and will be restored when Sumisho Air files its annual report on Form 10-K in early 2027.  During this period, the company plans to timely and voluntarily file all reports that it would otherwise have been required to file under Exchange Act Section 15(d), such that there will be no gap in its reporting.  Therefore, Sumisho Air argued that it will continue to satisfy the requirements to use Form S-3, notwithstanding that it may not be subject to the reporting requirements of Section 12 or Section 15(d) of the Exchange Act during that time.  The Staff agreed not to recommend enforcement action against Sumisho Air based on the foregoing. 

As noted in its letter, Sumisho Air plans to (i) continue offering and selling securities registered on an existing shelf registration statement during the period in which it is voluntarily reporting and after it files its next Form 10-K and (ii) file a new Form S-3 in reliance on the Staff’s guidance.  In other words, the relief can be interpreted broadly, enabling companies to both use existing registration statements and file new registration statements.

There is a strong policy rationale for the Staff’s decision, as noted in Sumisho Air’s letter, “a determination of Form S-3 eligibility should turn on ‘whether investors can readily obtain issuer-specific information . . . to make an informed investment decision.’”  Here, investors have such access; “[w]here an issuer has maintained an uninterrupted record of timely Exchange Act reporting, the purpose of General Instruction I.A.3 is satisfied regardless of the legal compulsion underlying any individual filing.”  Further, timely and flexible access to the capital markets is important to many public companies, including Sumisho Air, and this relief will likely increase the attractiveness of the U.S. capital markets.  The relief is also consistent with this summer’s proposing release on registered offering reform, which proposed eliminating the 12-month reporting lookback in determining Form S-3 eligibility, while retaining the requirements that companies be current and timely in their Exchange Act reporting (read more here).

The Staff revised Securities Act Forms CFI 115.15 in a manner consistent with the guidance in the letter.  The CFI states that, in order to be eligible to use Form S-3, an issuer must have been subject to the requirements of Exchange Act Section 12 or 15(d) for a period of at least 12 months.  However, this requirement can be satisfied if an issuer timely filed its Exchange Act reports during the past 12 months, but was not subject to Section 12 or 15(d) for some of that time, and instead reported on a voluntary basis.  Find the no-action letter here and the new CFI here.

On October 15, 2026, the Securities and Exchange Commission (“SEC”) approved amendments to Rule 2210 (Communications with the Public) of the Financial Industry Regulatory Authority, Inc. (“FINRA”), allowing member firms to project performance or provide a targeted return with respect to a security, a securities portfolio, or an asset allocation or other investment strategy in communications with the public, subject to specified conditions (the “Amendments”). Such conditions include (i) adopting and implementing written policies and procedures reasonably designed to ensure the communication is relevant to the likely financial situation and investment objectives of its intended audience, (ii) providing sufficient disclosure regarding the criteria and assumptions underlying the projected performance or targeted return and the risks and limitations of using the projected performance or targeted return in making investment decisions and (iii) maintaining records concerning the source of the projected performance or targeted return.

The Amendments further align the use of projected performance and targeted returns by broker-dealers under FINRA Rule 2210 with the use of hypothetical performance by SEC-registered investment advisers under Rule 206(4)-1 under the Investment Advisers Act of 1940 (the “Marketing Rule”).

However, FINRA did not, at this time, expand the scope of the Amendments to include additional categories of performance information, such as back-tested, model portfolio, related and extracted performance, thereby leaving a gap between FINRA Rule 2210 and the Marketing Rule. Broker-dealers must continue to rely on existing guidance in order to share this type of information with certain sophisticated investors under certain circumstances. Communications that contain both back-tested performance and projected performance and targeted returns must continue to be reviewed for compliance with applicable rules and guidance.

Continue reading this Legal Update.

On October 21, 2026, the Financial Industry Regulatory Authority, Inc. (“FINRA”) published Regulatory Notice 26-19 announcing amendments to FINRA Rule 5110 (Corporate Financing Rule – Underwriting Terms and Arrangements) and Rule 5123 (Private Placements of Securities).  The amendments are part of FINRA’s broader effort to modernize its rules and facilitate capital formation.

The amendments to Rule 5110, effective December 21, 2026, revise how securities treated as underwriting compensation are valued, replacing the existing “bona fide public market” standard with a valuation based on closing market prices on the acquisition date.  The amendments also add exclusions for certain securities acquired in debt-for-equity exchanges and for capital investments in direct participation programs and unlisted REITs, extend existing treatment to certain non-convertible preferred securities and clarify requirements applicable to termination fees and tail fees.

The amendments to Rule 5123, effective October 21, 2026, expand the existing private placement filing exemption to include certain entities owning more than $5 million in investments and qualifying family offices with more than $5 million in assets under management.  These changes reduce filing obligations for offerings sold to sophisticated investors and align the exemptions that are available from FINRA’s filing requirements with the SEC’s expanded definition of “accredited investor.”  We had previously posted regarding these changes.

Separately, the Securities and Exchange Commission (“SEC”) approved FINRA’s proposed rule change to exempt qualifying collective investment trusts (“CITs”) from FINRA Rules 5130 and 5131(b) (see our prior post), which restrict purchases of new issues by restricted persons and prohibit certain allocations commonly referred to as “spinning.”  The exemption is available to qualifying CITs that are not formed or maintained for the specific purpose of permitting restricted persons to invest in new issues.  FINRA will announce the effective date of the CIT exemption in a separate Regulatory Notice.

Together, these changes reflect FINRA’s continuing efforts to simplify its regulatory framework while maintaining investor protections.  Member firms should review their underwriting arrangements, private placement filing procedures and new issue allocation practices to assess the impact of the changes.

Access the FINRA Regulatory Notice.

Access the SEC Order.